AI Commerce Operator
An Arabic-first AI operator for online stores: the merchant types what they want in Arabic — add this item, change that price, reserve it for a customer — and the agent executes it.
At a glance
- Paying customers
- 1
- Contract value
- KWD 650/yr
- Implied ARPU
- KWD 54/mo
- Revenue concentration
- 100%
- Target wedge
- Unique-item
- Reachable merchants
- 85–100k
- App-store distribution
- Not yet live
- Agent language
- Arabic-first
One live deployment
Paid a full year up front
Paid annually, a year in advance
A single account
Antiques, vintage, jewellery, art
Salla + Zid, GCC. Author estimate
Salla App Store, Zid Market
Merchant instructs in plain Arabic
About
This is not a store builder. It is the layer that lets a non-technical Arabic-speaking merchant run a store without learning software.
The merchant photographs an item and describes what they want in plain Arabic. The agent writes the title, description and category, suggests a price, and publishes it — collapsing the single most expensive recurring task in unique-item retail. A simple/advanced mode toggle keeps the full admin surface available without putting it in the way, because most merchants never need it.
The problem
Gulf merchants who sell online split into two groups. The technical minority use Shopify, Salla or Zid comfortably. The large majority run their business from Instagram and WhatsApp, because every real e-commerce admin panel fails them in the same three ways.
They are English-first in structure even when the interface is translated — the mental model is foreign. They are built for catalogue products, where one SKU has many units. And they demand too many screens: images, title, description, category, price, inventory, variants, SEO fields, for every single object.
That last point is why an AI operator matters more here than in ordinary retail. A merchant selling one-of-a-kind items — antiques, vintage, jewellery, art, used luxury, collectibles, salvaged parts — has to create a full listing for every object they own. In unique-item commerce, the cost of listing is the business's main bottleneck, and the store simply never gets built.
What we built
The merchant works in Arabic and the agent does the rest. Photograph an item, say what you want, and it is written, categorised, priced and published.
The strategic decision that shapes everything else is what we deliberately do not build. Salla powers over 68,000 active merchants and has processed more than USD 13.3 billion in GMV; Zid has raised USD 59 million and is expanding across payments and shipping. Both are Arabic-native, government-aligned, capital-rich, and already own the merchant relationship. A storefront stack competing with them loses.
So we do not compete with them — we distribute through them. Salla's App Store and Zid's Market are established channels for third-party tools. That is 68,000+ merchants of instant distribution, no storefront to maintain, and a customer acquisition cost far below direct sales. Becoming their app rather than their rival is the whole plan.
Market
Kuwait alone is too small to matter here — a few thousand online merchants, most of them on Instagram. Worth saying plainly and moving on.
The real market is the merchant base of the platforms themselves: Salla's 68,000-plus plus Zid's, GCC-wide, gives roughly 85,000–100,000 reachable merchants. Narrowing to the non-technical merchants with high SKU churn — perhaps 15% — gives a serviceable market of 13,000–15,000. At 5–8% of that over three years, 650–1,200 customers, the modelled range is KWD 250–460k of ARR.
The cross-check is simple: 1,000 customers at KWD 32 a month is KWD 384k ARR. That is a genuine venture-scale trajectory — but only if distribution runs through the platforms rather than through our own sales calls. A direct-sales-only version of this business tops out in the low tens of thousands and is not fundable. The distribution strategy is the investment thesis.
Saudi e-commerce is estimated at USD 31.29 billion in 2026, projected to reach USD 54.87 billion by 2031. The wedge is small; the market it sits inside is not.
Business model
Two revenue lines, deliberately sequenced.
Subscription first, tiered by store size and agent actions: Starter at KWD 15 a month for under 100 items with capped agent actions, Growth at KWD 35 for unlimited items and full agent with image classification, and Pro at KWD 65 for multi-user access, bulk operations and priority processing, with annual at ten times monthly. The existing customer sits at Pro annual, which is what validates the top tier.
Marketplace distribution second, from year two. Once live on the Salla and Zid app stores, those platforms handle billing and take a revenue share — lower margin per customer, dramatically lower acquisition cost.
On modelled economics: a blended KWD 32 ARPU against KWD 6 of inference, KWD 2 of hosting and KWD 3 of support leaves KWD 21 of monthly contribution, a 66% margin. Direct sales cost around KWD 150 per customer and pay back in 7.1 months; app-store acquisition costs around KWD 40 and pays back in 1.9. At 4% monthly churn that is an LTV near KWD 525 — 3.5:1 against direct sales, 13:1 through the app stores. That gap is the entire argument for the distribution strategy.
One cost to name explicitly, because ordinary SaaS does not carry it: inference and image processing scale with usage rather than with subscribers. An uncapped AI tier at KWD 15 can lose money on a single heavy user, so agent actions are capped by tier by design.
Traction
One paying customer on a KWD 650 annual contract — an implied ARPU of KWD 54 a month. Someone paid a full year up front, which is stronger evidence than a monthly trial. That is the good news, and it is real.
The sample size is the problem. One customer is an anecdote, and everything modelled above rests on whether it generalises. Revenue concentration is 100%.
The live deployment is antiquekhana.com, an Arabic art-archive store selling vinyl, cassettes, magazines, photographs, books and documents — exactly the unique-item wedge the product is aimed at, which makes it a genuinely useful reference rather than a convenient one.
And the question that has to be answered before any pitch, because an investor will find it anyway: was that a product deployment or a bespoke build? If a general platform was configured for them, this is a product with one customer. If a custom system was built, this is an agency with one client — a different business, a different valuation. The only proof that settles it is customer two and customer three onboarded with zero custom code, and that is the first milestone this round has to hit.
Use of funds
- Product — de-customisation, multi-tenancy, reliabilityKWD 16,000 · 29%
- Salla and Zid app-store integrationsKWD 12,000 · 22%
- Sales and Arabic content marketingKWD 10,000 · 18%
- Legal counsel — the convertible instrument, app-store agreements and IP assignmentKWD 3,500 · 6%
- Licensing, insurance, bufferKWD 5,500 · 10%
- Inference, infrastructure, hostingKWD 8,000 · 15%
What this round delivers
- 50 paying customers, none requiring custom code
- KWD 20,000 ARR
- Live and approved on the Salla App Store
- No customer above 10% of revenue
- Published case studies with measured listing-time reduction
- Agent task success rate above 95%, measured and reported
Who is behind this
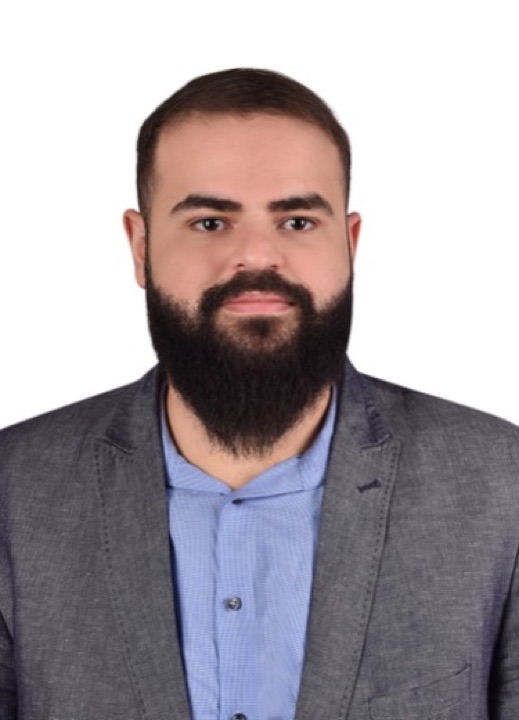
Omar Al-Othman
Founder & CEO
Omar Al-Othman founded Bara Al Sandoog and runs it. He is an electrical engineer by training and a software engineer by practice — and he has built each of these products himself.
More about Omar- Sector
- AI · Commerce infrastructure
- Stage
- Building
- Based in
- Kuwait
- Total raised
- KWD 9,500